Weekend geopolitics, Monday futures green
What happened
Friday’s cash tape was muted after Thursday’s chip relief. The Dow closed at 51,682.64 (−0.18%), the S&P 500 at 7,650.50 (+0.17%), and the Nasdaq Composite at 26,522.55 (+0.40%). For the week the Dow fell 1.7%, the S&P roughly 0.1%, and only the Nasdaq finished green (+0.7%). The 10-year Treasury yield finished Friday near 5.00%. Over the weekend Yemen’s Houthis claimed missile and drone strikes on Riyadh, while Treasury Secretary Scott Bessent and Chinese Vice Premier He Lifeng held talks in New York ahead of Thursday’s Trump–Xi meeting. Into Monday’s Asia session, S&P 500 futures were about 0.4% higher and Nasdaq futures about 0.6% higher; South Korea’s tech-heavy index gained roughly 1.1%–1.5% while Japan stayed shut for Silver Week.
What it means
The week’s map is diplomacy versus energy risk. Tariff, AI-governance, and critical- minerals headlines around Trump–Xi support growth and semiconductor sentiment if talks stay constructive — Asia’s AI-linked tape already lifted overnight. The Houthi strike keeps Middle East shipping and crude volatility in play even as Monday wraps showed oil easing on talk of recovering Saudi export flows (Brent near $101.63, about −2.1%; WTI near $98.15). Sticky yields near 5% and roughly 56% odds of another Fed hike in October still pressure rate-sensitive banks and small caps after the Dow’s third losing week. Breadth on Friday was weak — decliners led advancers — so a soft-green futures open does not erase last week’s digestion.
Chart and trend facts
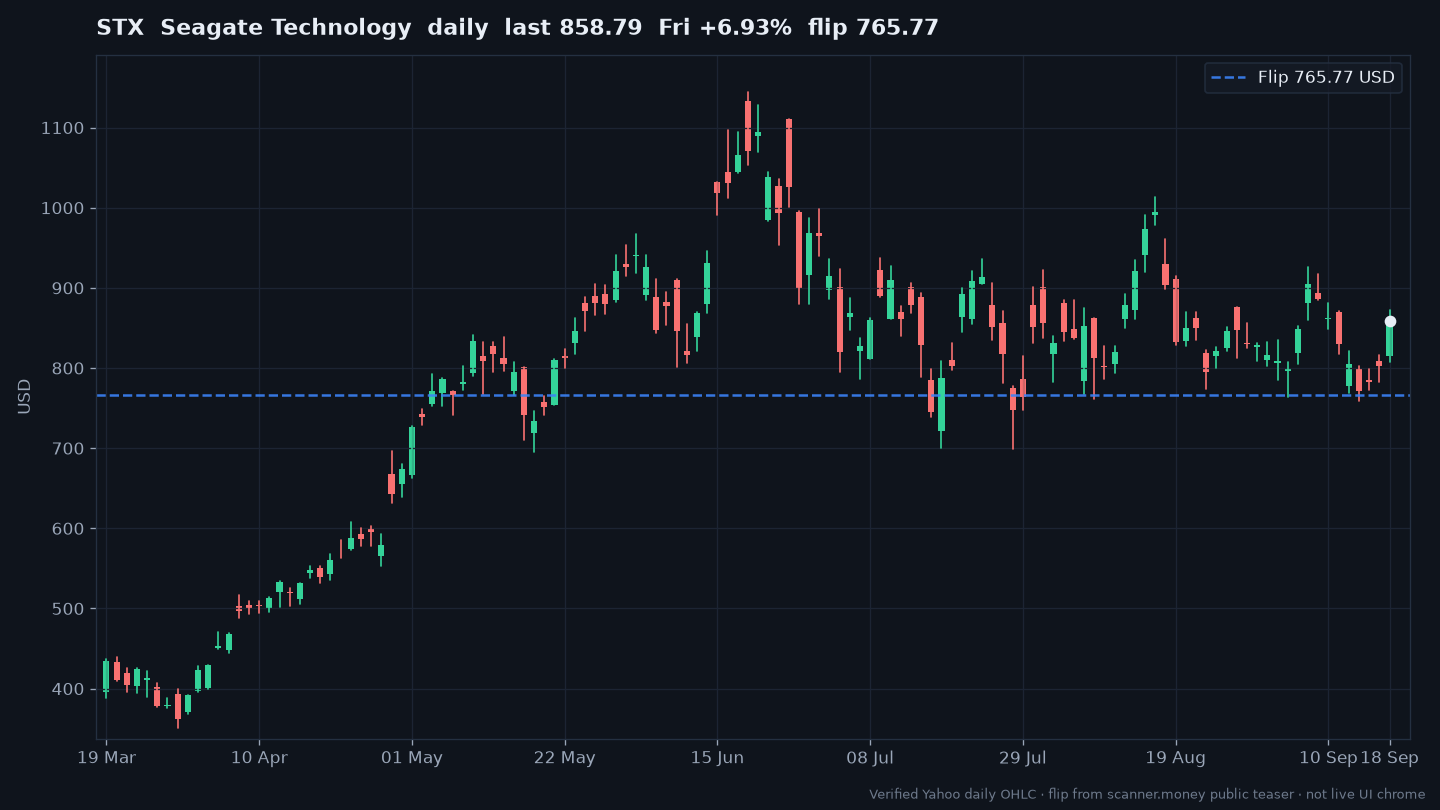
Verified Friday closes: Dow −0.18%, S&P +0.17%, Nasdaq +0.40%, Russell 2000 −0.50%. Early Monday wraps show equity futures modestly higher and Asia tech leading while Japan is closed. Oil cooled from Friday’s still-above-$100 closes but remains the inflation wildcard into the open.
What to do
Treat the overnight bounce as positioning into a diplomacy-heavy week, not confirmation that the hawkish path or energy risk is cleared. Prefer watching cash hours before adding size.