Oil and yields eased; chips led the rebound
What happened
After Wednesday’s first Fed hike in three years to a 3.75%–4.00% funds target, Thursday cash reversed the scare. Brent settled about 1% lower near $104.82 a barrel, and the 10-year Treasury yield slipped to roughly 4.93% from about 5.01% late Wednesday. The Dow closed at 51,778.04 (+0.61%), the S&P 500 at 7,637.76 (+1.14%), and the Nasdaq Composite at 26,418.30 (+1.69%). The Philadelphia Semiconductor Index rose 3.14% to 11,599.49, with 29 of 30 constituents higher.
What it means
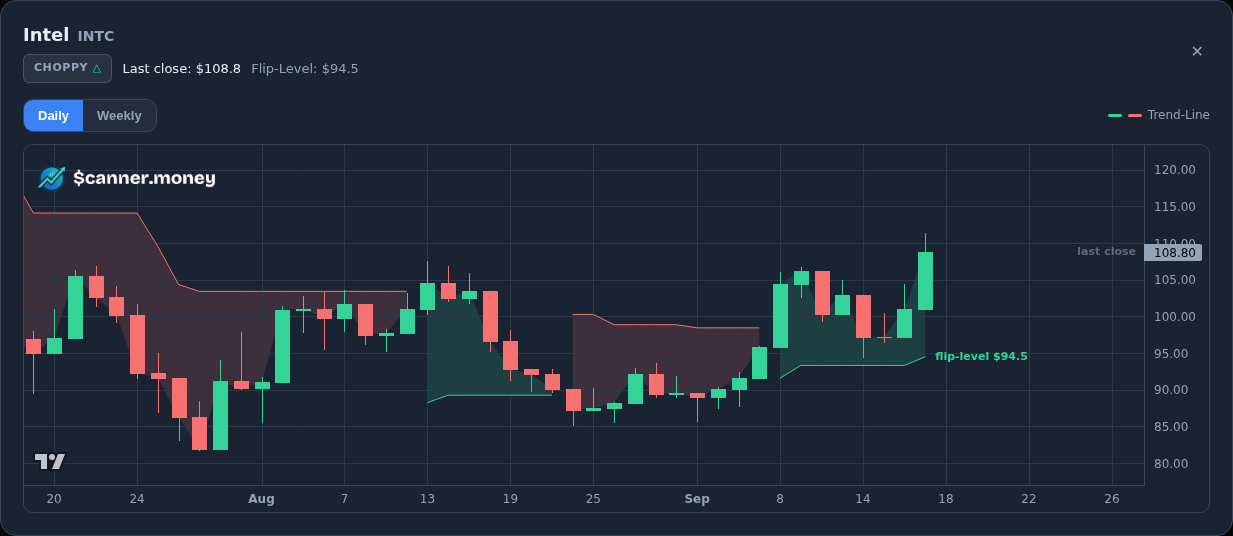
The hike itself was widely expected; what mattered Thursday was the relief channel — softer oil and cooler long yields took pressure off growth duration. Semis and memory reclaimed leadership after earlier AI-spend jitters: Arm about +8.6%, Intel about +7.7%, AMD about +6.4%, SanDisk about +6.2%, Micron about +5.5%, with Nvidia about +2.5% and Broadcom about +2.3%. Foundry and memory supply-chain names moved with the tape (TSMC about +3.0%; storage peers Seagate and Western Digital also green). Rate- sensitive banks that sold hard Wednesday got a quieter digestion day rather than a full mean-reversion sprint. Energy producers face a third session of softer crude into Friday while prices remain above $100, so the inflation-input story is cooler, not closed.
Chart and trend facts
Verified Thursday closes only: Dow +0.61%, S&P +1.14%, Nasdaq +1.69%, SOX +3.14%. Early Friday wraps show equity futures modestly red after that bounce, with oil still above $100 but extending losses about 1% in overnight trade. Fed speakers Michelle Bowman and Jeffrey Schmid are on the Friday calendar for more path commentary.
What to do
Treat Thursday as a relief session after the hike, not a green light to add size into a soft Friday futures open. Prefer watching cash hours confirm before scaling chip or growth exposure that already ran hard.