Two red sessions; futures quiet into the print
What happened
Tuesday cash closed lower again. The Dow finished at 52,093.11 (−0.63%), the S&P 500 at 7,585.73 (−0.45%), and the Nasdaq Composite at 25,981.57 (−0.78%). The 10-year yield touched about 5.041% intraday — the highest since July 2007 — and settled near 5%. Brent settled above $108 a barrel, with WTI still above roughly $100. Wednesday premarket, Dow futures sat near 52,200 (+0.16%), S&P futures near 7,601.50 (+0.16%), and Nasdaq futures near 28,991. Markets still price roughly a 90–95% chance of a 25 bp hike to 3.75–4.00%, with the decision and SEPs due around 14:00 ET.
What it means
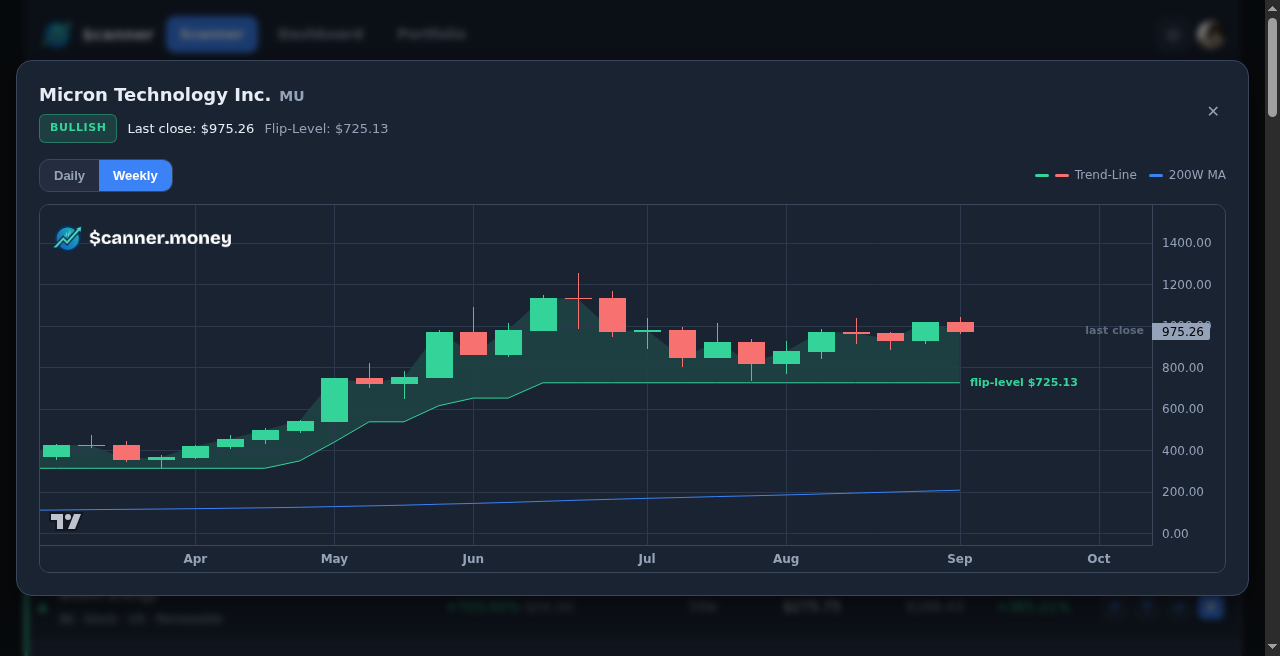
A tiny futures bounce after two down sessions is not a regime change. Yields at five and oil above $108 keep duration and crowded growth under pressure into the press conference. Names already in long weekly trends — Micron (MU), Bloom Energy (BE), Seagate (STX), Dell (DELL), and Siemens Energy (ENR.DE) — do not need a fresh entry before the path is clear. Credit-sensitive AI and hardware betas remain the most exposed if dots or guidance lean hawkish.
Chart and trend facts
Last completed weekly scan remains Sunday 13 September. Those prints still show the same bullish weekly cluster above flip. Two cash sessions of pressure stressed holders of that group; the weekly flip prints have not been refreshed.
What to do
Sit in cash unless you already hold a confirmed weekly trend. Do not invent a Wednesday morning entry from a flat futures open with the decision still hours away.